Brigit: Cash Advance & Credit

- 41.77K Reviews
- 4.8
- Downloads
- 5,000,000+
 Analysis by Mobxio
I think Brigit makes the most sense when a small timing gap is the problem, not when someone needs a long-term fix for debt or a shortfall that keeps growing. It brings several money-management tools together, but I’d treat any advance as a bridge to the next deposit rather than extra spending money. That distinction matters: a quick transfer can soften a difficult week, yet it cannot make an underlying budget gap disappear.
Where the app fits in everyday money management
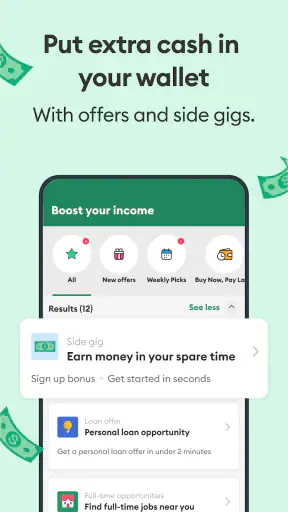
Brigit is a finance app from Brigit, and its focus is practical: cash advances, personal loans, credit-building options, and saving. The current version is 1043.0, while the app has been available since April 16, 2018. That long-running presence gives it a more established feel than a brand-new cash-advance product, although longevity alone is not a reason to borrow. I’d still judge it by whether its available tools match my own cash flow and whether I can repay comfortably.
The app is free to download, and it is rated for Everyone. Its overall store rating is 4.8 from around 312,000 ratings, with roughly 42,000 written reviews and over 5 million installs. Those figures suggest that many people have tried it, but they don’t tell me whether a particular user will qualify for an advance or find the terms suitable. I would go through the offer details in the app before relying on any money arriving by a particular time.
One useful way to think about Brigit is as a set of separate decisions rather than one all-purpose solution. A cash advance addresses timing, a personal loan is a different kind of borrowing decision, credit-building is a longer project, and saving is about creating a cushion. Choosing the right lane matters. If I only need help making a bill date line up with payday, I would not automatically assume that a loan or credit product is the best answer.
What an advance can—and cannot—solve
Picture a routine week: a paycheck is due soon, but a necessary expense lands a few days earlier than expected. An advance may help cover that mismatch and reduce the chance that a low balance disrupts another payment. In that situation, I’d first check the bill’s due date, the amount I can safely repay, and whether the advance would leave enough for essentials afterward. If repayment simply pushes the same shortage into the next pay period, the convenience may be temporary rather than genuinely helpful.
That is why I wouldn’t build a monthly budget around advances. They can be useful as occasional backup, but repeated borrowing is a sign to review the dates and amounts of regular bills, contact a provider about changing a due date when possible, or look for a more durable adjustment. A small emergency fund—even one built gradually—can eventually give more flexibility than depending on a transfer each time an expense arrives early.
Before accepting an offer, I’d also read the repayment and delivery details shown for that specific transaction. A product can be described broadly as an advance while the practical timing and conditions still matter to the person using it. Don’t plan around money until the app confirms the offer and you understand when it is expected to arrive. If a bill is due immediately, contacting the biller may be a better first move than assuming an app transfer will meet the deadline.
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
Making the other tools work harder
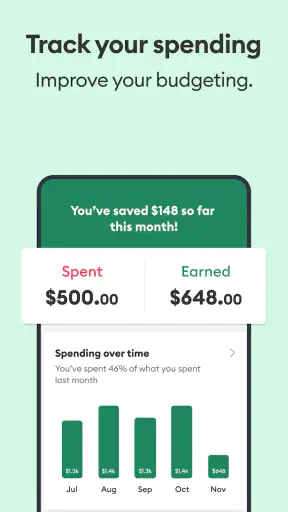
The budgeting side can be more valuable when I use it to answer a specific question instead of browsing spending summaries without a goal. For example, I might look for recurring charges that cluster just before payday, or compare a week with several automatic payments against a quieter one. That can reveal a cash-flow pattern that a simple account balance misses. The practical follow-up is to adjust a payment date or set aside money earlier, rather than merely noting that a week felt expensive.
For credit-building, I’d treat the option as a deliberate, longer-term commitment and read its terms before enrolling. Credit improvement is not an instant result, and no app can promise a particular score change. Someone whose immediate priority is avoiding a missed payment should focus first on the payment itself; someone with room in the budget and a clear goal may find a credit-building product more relevant. Keeping those purposes separate helps prevent borrowing for one reason while expecting a different benefit.
The saving tools also work best when the target is concrete. I’d start with a modest buffer for a predictable expense, such as a utility bill that varies or a routine household purchase, then choose an amount that does not interfere with essentials. A savings habit is less dramatic than an advance, but it gradually reduces the number of emergencies that require one. If setting money aside makes the next few days unaffordable, the target is too ambitious for now.
Who may prefer another option
Brigit is most appealing to someone who wants several money tools in one place and sometimes faces a short gap between expenses and incoming pay. It may be less suitable for a person who needs a guaranteed amount by a fixed hour, cannot confidently manage repayment, or is already using borrowing to cover ordinary monthly costs. In those cases, a lender or service with terms that better fit the situation—or a direct conversation with a creditor—may be a safer route than accepting the first available advance.
Compared with a bank overdraft, an advance app may feel more intentional because I can review an offer before using it; an overdraft, by contrast, is tied to the account and the bank’s rules. But neither should be assumed to be cheaper or more convenient without checking the actual terms. Compared with a credit card, an advance does not serve the same purpose as a revolving line for planned purchases, and a card’s costs and repayment structure can differ substantially. I’d compare the specific costs, due dates, and consequences rather than rely on the product label.
A bank’s own budgeting features may be enough for someone who mainly wants spending visibility and does not need Brigit’s borrowing or credit tools. Conversely, someone who wants a single-purpose budgeting app may find Brigit’s broader set of financial options unnecessary. The best choice depends on the problem I’m solving: tracking, a short cash-flow bridge, credit-building, or a longer-term loan are not interchangeable needs.
One practical habit is to keep a note of why I used an advance and what expense triggered it. After a few uses, that record can show whether the issue is truly occasional or tied to a recurring bill cycle. If the same kind of shortfall keeps appearing, I’d use that pattern to revise the budget or seek a more stable arrangement instead of treating each new advance as an isolated surprise.
Getting Started with Brigit
First things first, setting up Brigit: Cash Advance & Credit is as easy as pie. Once you download the app, it’s a straightforward process to link your bank account. Don't worry, they’ve got top-notch security measures in place, so your data's safe and sound. After linking up, Brigit analyzes your spending habits to offer you cash advances and credit-building tools.
Why Brigit Stands Out
What sets Brigit apart is its simplicity and user-friendly interface. The app design is clean, and navigating through it is a breeze. You can instantly see how much cash advance you're eligible for, and the best part? It’s interest-free. Yes, you heard that right! No hidden fees or surprise charges lurking in the shadows.
Another cool feature is the budgeting tool. It breaks down your expenses, offering insights on where you might be overspending. It’s like having a financial advisor right in your pocket. Plus, if you’re aiming to build or improve your credit, Brigit offers a credit-builder loan that reports to the major credit bureaus. That’s a huge win for anyone looking to boost their credit score.
The Little Things That Matter
Brigit comes with some nifty features that add to its charm. The automatic transfer option is a lifesaver. No more worrying about getting hit with overdraft fees because the app predicts when you might run short on cash and sends you an advance to cover it. It’s like having a financial buddy watching your back.
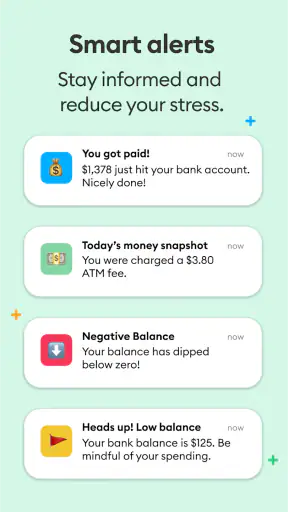
And let’s not forget the notifications. Brigit sends friendly reminders about upcoming bills and potential overdrafts. It’s like having your own personal assistant gently nudging you to stay on track.
Final Thoughts
All in all, Brigit: Cash Advance & Credit is a solid choice for anyone looking to manage their finances more effectively. It’s user-friendly, reliable, and, most importantly, it actually helps you out when you’re in a financial bind. So, if you’re tired of stressing over unexpected expenses or looking to build your credit, give Brigit a whirl. It might just be the app you didn’t know you needed.
Remember, financial stability is just an app away, and Brigit might just be the perfect partner in your journey to better money management.
What I’d check before relying on it
The app’s version number shows its current software state, but it does not by itself tell me which features have changed over time. I would avoid assuming that a newer version means a particular tool, eligibility rule, or transfer process has changed. Existing users should check the in-app details when an offer or screen looks different, especially before accepting a new advance or starting a credit-related product.
For a first-time user, the key questions are straightforward: what amount is actually available to me, when would it arrive, what must I repay and when, and what happens if my pay timing changes? I’d also check whether the account connection and requested information feel appropriate before continuing. Those checks are more useful than relying on a general impression of the app, because the answer can depend on an individual account and offer.
For someone already using Brigit, I’d periodically review whether the app is helping reduce stress or simply making it easier to repeat the same borrowing cycle. If advances are becoming routine, pause and work through the budget and bill timing features first. If they remain occasional and repayment fits comfortably, the app can serve as a convenient backup while saving and planning do the longer-term work.
My overall view is positive but measured: Brigit brings cash-flow support and broader financial tools together in an accessible package, and that combination can be useful when I know exactly what I need from it. I would recommend trying it to someone who wants to inspect those options, not to someone expecting an app to replace a sustainable budget or guarantee money on demand. Use the tools with a clear purpose, verify each offer, and keep the next payday’s essentials in view before borrowing.
Brigit: Cash Advance & Credit FAQ
What is Brigit and how does it work?
Brigit is a financial app available on Android and iOS designed to help users manage their finances by providing cash advances, budgeting tools, and credit monitoring. Once you connect your bank account, Brigit analyzes your spending patterns to predict cash shortfalls, offering advances up to $250 to cover expenses without the hassle of traditional loans.
Is Brigit safe to use with my bank account information?
Brigit uses bank-level security measures to protect your personal and financial information. The app employs 256-bit encryption and does not store your bank login credentials. Additionally, it is designed only to view your transaction data, ensuring your financial details remain secure and private.
Are there any fees associated with using Brigit?
Brigit offers a free version with limited features, but to access cash advances and additional tools like credit monitoring, users need to subscribe to Brigit Plus. The subscription typically costs around $9.99 per month, providing comprehensive financial planning and support services.
How quickly can I receive a cash advance from Brigit?
Once approved, Brigit can deposit the cash advance directly into your linked bank account. Typically, funds are available within one business day, though the exact timing can depend on your bank's processing speeds. Brigit also offers an optional Express Delivery feature for faster access.
Can Brigit help improve my credit score?
Yes, Brigit offers credit monitoring tools that help you track your credit score and provide personalized tips to enhance it. While direct cash advances do not impact your credit score, responsible financial management with Brigit's budgeting tools can contribute to long-term credit improvement.
The Best Parts of Brigit: Cash Advance & Credit
Things to Keep in Mind About Brigit: Cash Advance & Credit